
Anthropic's 45% quarter left IPO investors wanting more
If you were planning to buy into Anthropic's November IPO, or already hold its private shares, the valuation investors are discussing has come down. Some current and prospective investors are now weighing around $1.5 trillion. They had previously expected roughly $2 trillion, Reuters reports, citing four people familiar with the matter. That talk comes amid wider concern about how much it costs to finance AI.
Per Reuters' sources, what let some investors down was the slower sequential growth: revenue rose 45% in the third quarter to $16.8 billion, after more than doubling in the second.
The lower figure came out of Anthropic's investor day at its San Francisco headquarters on Wednesday. Most of the people there were the company's best-known investors. They met CEO Dario Amodei and finance chief Krishna Rao. Three of Reuters' four sources said a valuation of around $1.5 trillion was discussed. None of this is an offer price. Nothing has been priced yet, and the sources spoke anonymously because they are not authorized to speak publicly.
Before → after
- Valuation investors expected for the November share sale: roughly $2 trillion → around $1.5 trillion now under discussion.
- Quarter-on-quarter revenue growth: more than doubled from Q1 to $11.6 billion in Q2 → up 45% to $16.8 billion in Q3.
The $2 trillion figure was only ever investor talk and was never confirmed. That means the drop is measured from an unofficial expectation, not from any number Anthropic published. There is a separate benchmark: analysts in June projected a listing range of $1.1–1.25 trillion. That was a different estimate made at a different time, and the $1.5 trillion under discussion now is still above it.
The growth figure varies slightly by outlet. Reuters gives 45%. According to Value Add VC, the Financial Times reported the same $16.8 billion on October 14 as growth of about 46%.
One quarter of revenue now exceeds Anthropic's whole 2025
On September 19 we reported what the Wall Street Journal said about the timing. According to the WSJ, advisers saw an upside in a November listing because it left room to share third-quarter financials. They said those numbers would show a strong competitive position even after OpenAI launched its Astra model in September. At the investor day, Anthropic said the quarter was profitable on an adjusted basis. Reuters does not say what the adjustments exclude.
Last year Anthropic's revenue grew twelvefold to nearly $4.6 billion. Its operating loss was more than $8 billion, excluding writedowns of liabilities mostly tied to earlier fundraising. The IPO prospectus Reuters saw in September reported a loss of $42 billion for 2025. It also argued that AI will change the global economy more deeply than industrialization, electricity and the internet did. On October 15 we noted, citing Bloomberg, that the Q3 figure alone was larger than all of 2025's revenue.
The curve before Q3 was much steeper. According to Value Add VC, Anthropic's annualized run rate was roughly $9–10 billion at the end of 2025. It reached $30 billion by April 2026 and $47 billion by May. The same outlet traces the private valuation like this: $18.4 billion (March 2024, Amazon), $61.5 billion (Series E, March 2025), $183 billion (Series F, September 2025), $380 billion (Series G, February 2026) and $965 billion (Series H, May 2026). On October 9 we covered an FT report that put Anthropic's run rate at $65 billion and OpenAI's at roughly $50 billion as of September.
The Series H closed on May 28, 2026. It raised $65 billion, the largest single venture round on record, and was led by Altimeter, Dragoneer, Greenoaks and Sequoia. Amazon, Micron, Samsung and SK Hynix also took part. According to Tastytrade, the round set the $965 billion post-money valuation, and Anthropic confidentially filed a draft S-1 with the SEC on June 1. Morgan Stanley, Goldman Sachs and JPMorgan are reported as lead underwriters, with Citi also named. Anthropic retained Wilson Sonsini, and the FT reported in December 2025 that the company was preparing for a possible 2026 IPO.
A tech selloff and a $518 billion commitment form the backdrop
The tech selloff has hit AI infrastructure companies, chipmakers and neoclouds, the providers that rent out AI computing power. Shares and bonds of Nvidia-backed CoreWeave fell on Thursday. Investors are growing more worried about an AI buildout that is increasingly paid for with borrowed money. The IPO market has had setbacks too: data center operator SB Energy delayed its listing last month, and nuclear technology company Holtec Nuclear dropped its plans to go public.
Anthropic has committed to spending at least $518 billion over a decade on cloud services, compute and infrastructure. That includes 5 GW from Amazon AWS and 5 GW of TPU infrastructure from Google and Broadcom. Google and Amazon are investors, compute suppliers, distribution partners and competitors all at once. Reuters reported from the prospectus that Broadcom would lend Anthropic up to $42 billion to lease chips. On October 6 we noted an FT headline about a record $60 billion chip deal for Broadcom and Anthropic, put together by Wall Street banks.
Reuters writes that a cooler reception could weigh on the wider AI market. Investors see that market's near-term prospects as depending largely on this sale, and then on OpenAI's possible listing next year.
The fragility argument came before the Q3 numbers. MESHLAUNCH argued that $965 billion on about $47 billion of annualized revenue already meant a price-to-sales multiple of around 20, which left little room if growth slowed after listing. The outlet also points out that financials stay private during a confidential filing, so pre-IPO secondary prices can end up far from the eventual offer price.
Our reading is that the spending commitment matters more for the final price than any single quarter's growth rate. A bill of at least $518 billion is easier to defend if 45% quarters keep coming, and much harder if they don't. In August we reported that bankers were basing the valuation on a revenue forecast of $190–200 billion for 2028.
Formal marketing could start the week of November 9
The schedule has already slipped more than once. According to Tastytrade, reports on August 27 expected a prospectus after Labor Day. On September 5, Reuters pointed to a prospectus in late September, marketing from mid-October at the earliest, and a listing targeted for the days after the November midterms. On October 15 we reported that formal IPO marketing could start as soon as the week of November 9. The roadshow is where a price range would replace investor talk, so that week is the next date to watch.
Up next
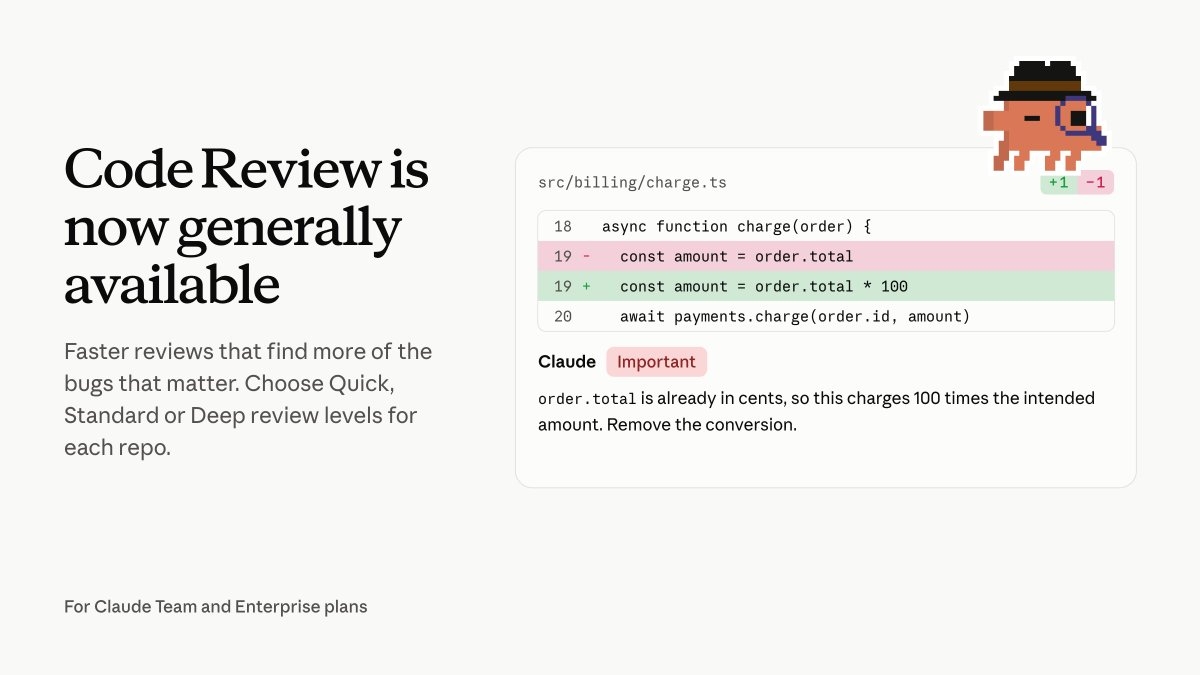
Claude Code Review exits preview and runs about 3x faster
Claude Code Review left research preview and cut most reviews from about 20 minutes to 6–10, with admins choosing Quick, Standard or Deep for each repo. Would you run Deep on every repo or save it for the critical ones?
Related stories
- Anthropic's $16.8B quarter tops its whole 2025 revenue
- A November IPO buys Anthropic time to show Q3 numbers
- Claude's free Team year for startups lasted only days
- Grok Bot will route tasks to Claude Opus 5.5, Musk says
- Claude Startups widens its door, with up to $45K in perks
- Wall Street banks launch a record $60B Anthropic chip deal
Comments
No comments yet. Be the first.
Join the conversation
Sign in to leave a comment. It appears after moderation.