
Fears of AI apocalypse crashed into Anthropic’s $2T IPO
A $2 trillion price for Anthropic works out to just seven times its 2028 sales, if the investors forecasting a $320 billion revenue run-rate by the end of next year turn out to be right. That is the starting point of a valuation analysis the FT published on September 21. It runs three methods, and on most of the variants the FT works through, $2 trillion comes out as the low end.
Anthropic was poised to file this month for an IPO at that valuation, until fears of an AI apocalypse broke into the mainstream. OpenAI has also been planning a listing, but Sam Altman has paused it until next year and called floating earlier “ill-advised”.
Seven times sales
The simplest method takes earnings, or revenue when there are no earnings, a year or two out and applies a multiple from listed peers. Anthropic makes that hard. It was founded in 2021 and had no revenue until 2023. By August it was making around $65 billion on an annualised basis, and the FT says unofficial numbers like that should be handled with kid gloves. Eighteen months ago, Anthropic expected its 2027 revenue to be only $12 billion.
Measured against that $65 billion run-rate, a $2 trillion valuation is about 31 times current revenue. The seven-times multiple holds only if the run-rate grows nearly fivefold by the end of 2027, and the investors forecasting that are not impartial. Seven times would still be a little below Microsoft’s multiple, per LSEG. SpaceX trades at 16 times its 2028 revenue. Use that as the benchmark and Anthropic could be worth $5 trillion. Wall Street priced SpaceX the same way: underwriters including Goldman Sachs and JPMorgan set their targets from profit one or two years out and a multiple taken from peers.
The private marks have moved fast as well. Anthropic’s valuation went from $61.5 billion in March 2025 to $183 billion in September 2025, $380 billion in February 2026 and $965 billion at the Series H, announced May 28. The confidential draft IPO filing followed on June 1. A $2 trillion listing would put a little more than twice the last private price on the company.
The TAM ladder
The second method starts from total addressable market (TAM): the size of the revenue pool a company could in theory capture. Its record is mixed. Uber cited a $12.3 trillion TAM when it listed in 2019, and its annual revenue today is under $60 billion. WeWork’s $3 trillion office market did not keep it out of bankruptcy.
SpaceX set the reference point. In its May listing documents it put the “enterprise apps” market at $22.7 trillion, a little more than the entire annual revenue of the S&P 500. Microsoft’s revenue is less than 2 per cent of that. If Anthropic captured 3 per cent, it would make nearly $700 billion a year. At 10 times revenue, discounted over three years, that gives $4.5 trillion.
The Wall Street Journal has reported that Anthropic’s filings may describe a market worth $30 trillion. Morgan Stanley, likely to be an underwriter on the IPO, last week estimated that generative AI could reach a market twice that size, covering “knowledge work” and digitisable consumer spending. If AI took 10 per cent of that $60 trillion, which would mean replacing about 100 million workers, and Anthropic took a third of AI’s share, it would have $2 trillion in annual revenue. With the same multiple and five years to get there, that gives $10 trillion today. The multiple stays at 10 throughout, so the answer is set almost entirely by which TAM you choose.
Then there is the bull case. Anthropic’s research arm has said AI could unlock more than $10 trillion of US GDP by 2030 under its “extreme” scenario of widespread adoption and highly productive AI. The FT’s rough maths puts that at $100 trillion of equity value.
Commodity cognition
The weak point is whether the labs keep the money. If models become interchangeable, the cheapest one sets the price. Palantir’s Alex Karp calls this “commodity cognition”: value goes to whoever owns the data or the application, and model makers earn enough to cover costs and not much more.
There are signs of this already. Moonshot AI’s Kimi and DeepSeek offer slightly lower quality at a much lower price. Meta and Alphabet can fund cheap or free models from their ad businesses. Google and OpenAI have cut prices on some of their less advanced offerings. Many customers, including some of Anthropic’s own investors and underwriters, run routing software that sends each task to the cheapest model that can handle it. Nvidia, an investor in both OpenAI and Anthropic, has bought Hugging Face, a major distribution platform for open-weight models, which increasingly compete with closed models on less advanced tasks.
Founders respond that the best models will always command a premium, because companies will pay top prices to solve the “hard 5 per cent” of problems. Some also expect recursive self-improvement, where models upgrade themselves with little or no human help, to give the winners a very wide moat.
Moving up the stack
Anthropic’s plug-in for lawyers, launched in January, set off the SaaSpocalypse. Salesforce, ServiceNow and other software makers lost a combined $300 billion in a couple of days. $2 trillion is less than a third of the combined market capitalisation of the software and services companies in the S&P 500. Marc Benioff calls the SaaSpocalypse “crazy nonsense”, yet Salesforce has since partnered with Anthropic on Claudeforce, which combines Claude models with Salesforce’s customer service products. OpenAI released its own legal research and writing tool, Astra for Law, on September 17.
Pricing the doom
Then there is the risk factor no other company’s model has to include. Amodei’s call this month for the labs to “pace the frontier”, together with warnings from former Anthropic researcher Jacob Coxon, has made those fears much louder. Extinction takes every investment to zero. A smaller disaster, such as the “hundreds of billions of dollars in damage” Amodei writes about in his recent essay, could cut deeply into Anthropic’s valuation if the company were held liable. In the days after his call, cybersecurity and antivirus stocks rose by double digits. The FT argues that a slowdown could help, because it would push the labs to earn more from the models they already have and to spend more carefully.
The IPO has now moved to a November listing, which leaves room to report third-quarter results. On October 14, after the analysis was published, the FT reported Q3 revenue of $16.8 billion, up about 46% from the second quarter.
Up next
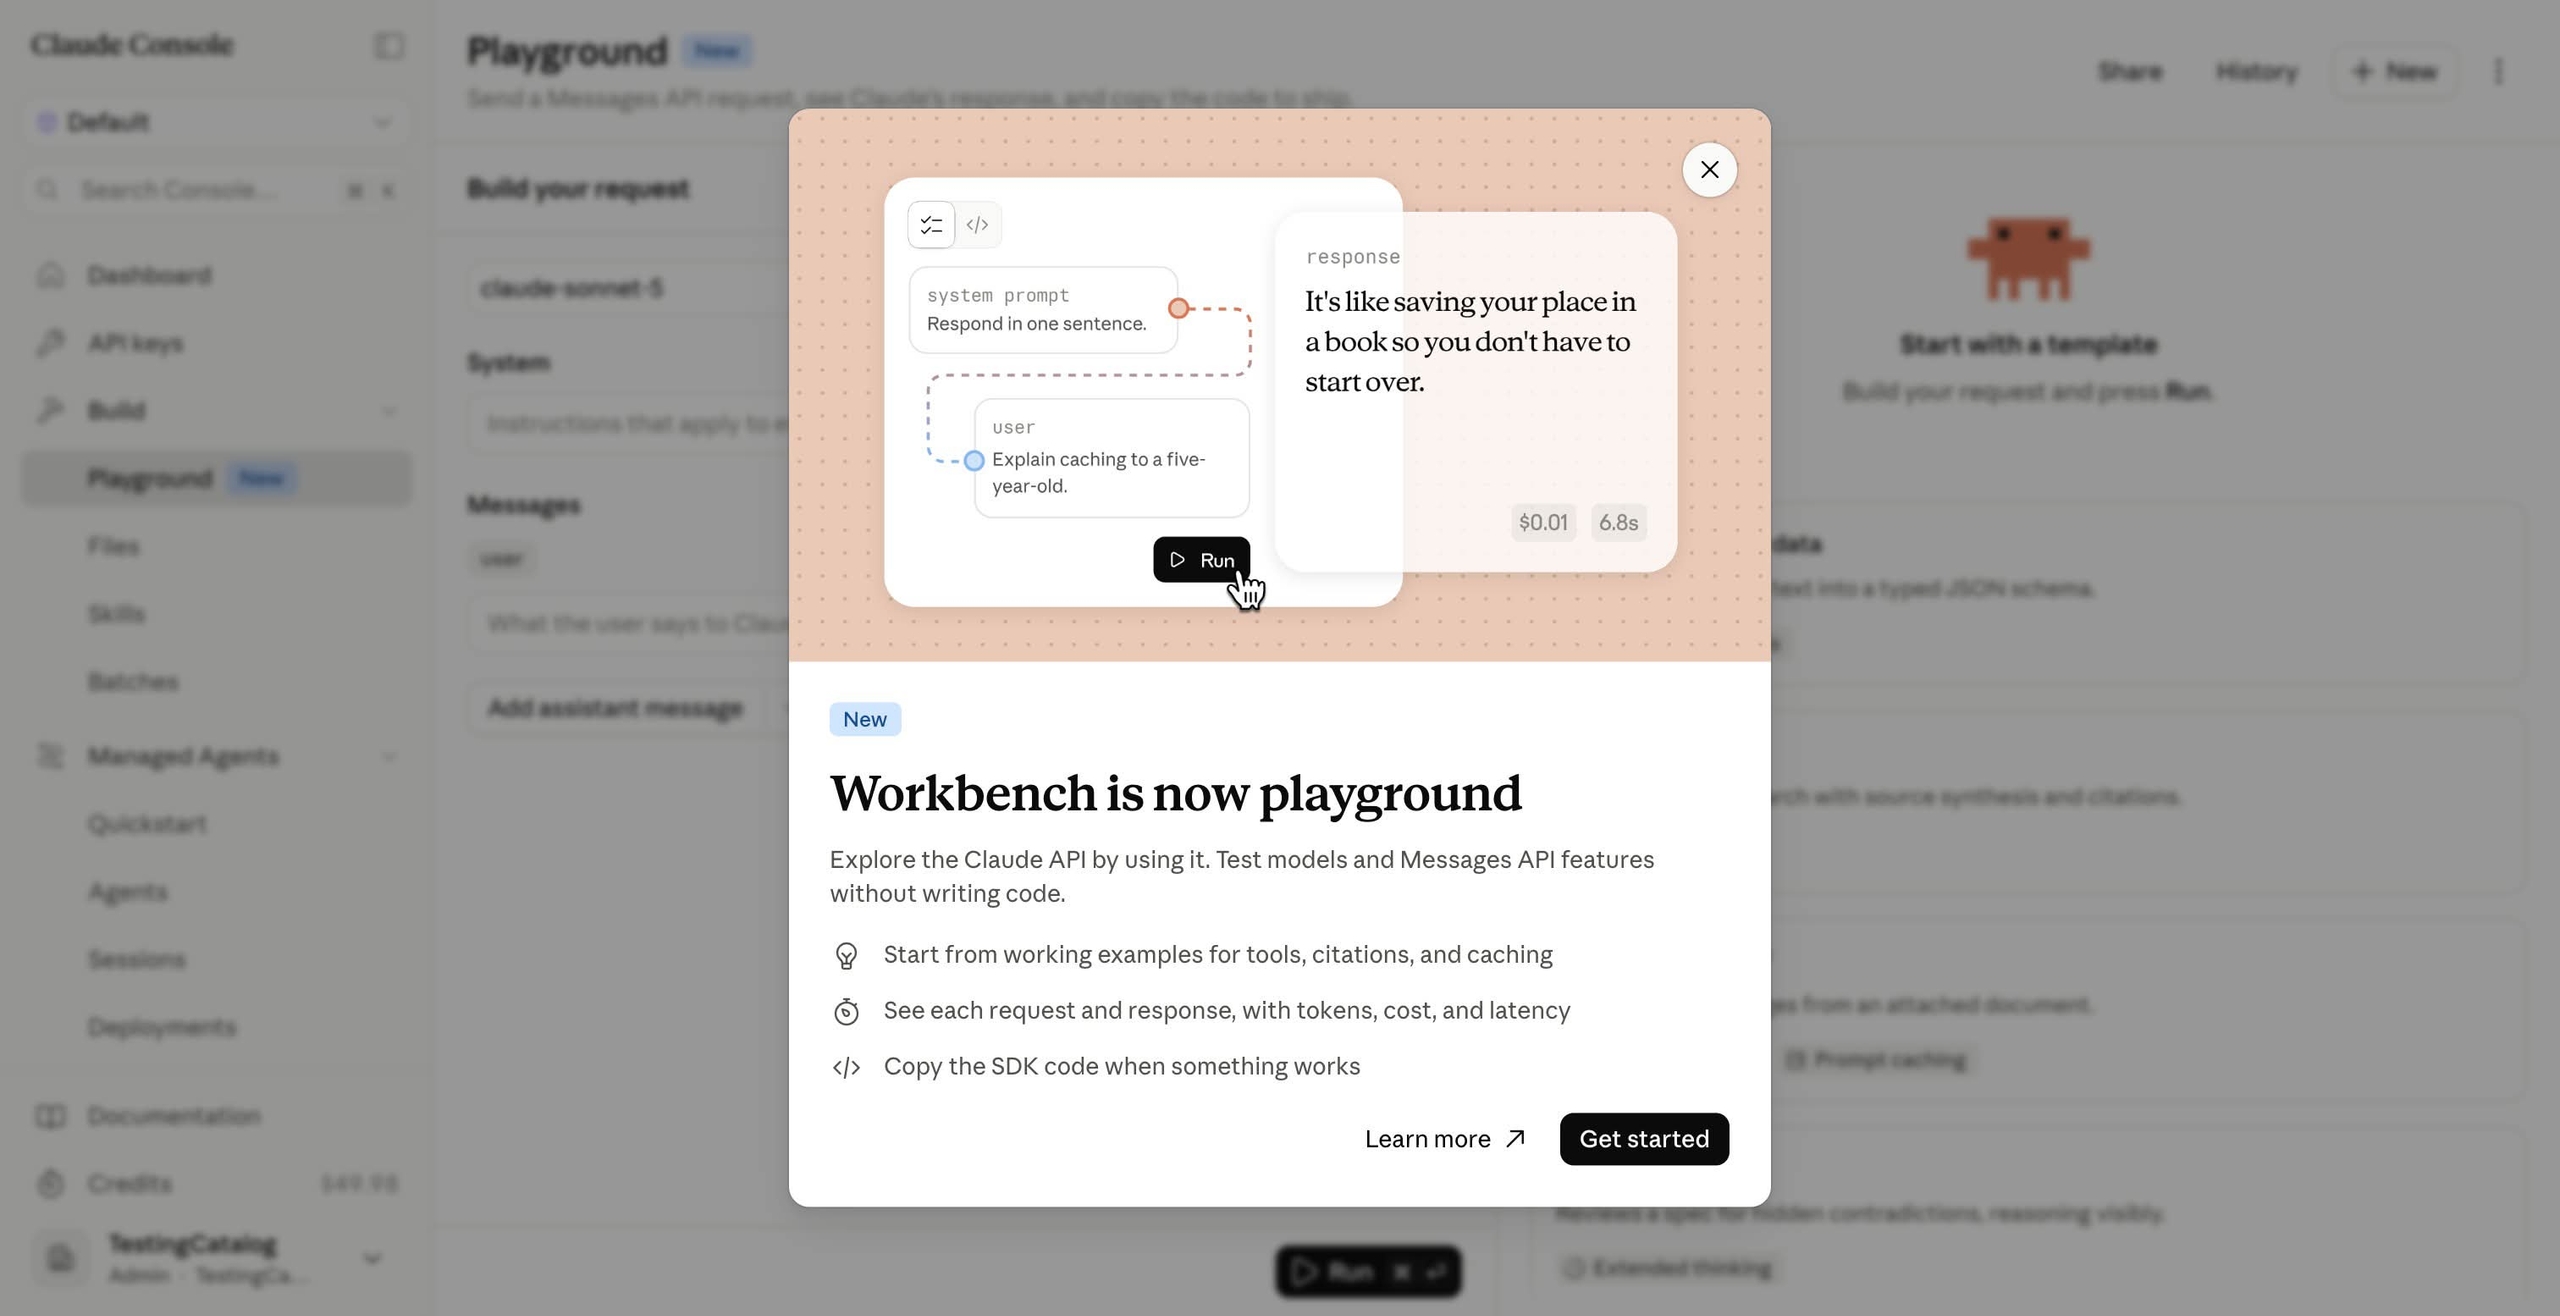
Claude’s API sandbox got a new name and a cost readout
Anthropic’s browser sandbox for the Claude API answers to Playground now, and every call comes back with its tokens, cost and latency, though it keeps no prompt history to go back to.
Related stories
- A November IPO buys Anthropic time to show Q3 numbers
- Anthropic’s IPO slips to a listing just before midterms
- Anthropic Sees over $30T in Potential Revenue
- A San Francisco home is up for sale, payable in OpenAI or Anthropic stock
- OpenAI delays IPO to 2027
- Anthropic’s business spend surpasses OpenAI’s for the first time
Comments
No comments yet. Be the first.
Join the conversation
Sign in to leave a comment. It appears after moderation.